TOM JOHNSON Rooming Accommodation Finance

Written by a developer who builds and holds his own rooming houses

NEW FREE PLAYBOOK REVEALS WHAT YOUR BROKER OR BANK MAY NOT BE SHOWING YOU

“WHY SOME ROOMING HOUSE INVESTORS PAY 8%+ WHILE OTHERS GET MAJOR-BANK PRICING ON THE SAME ASSET (FREE DOWNLOAD)”

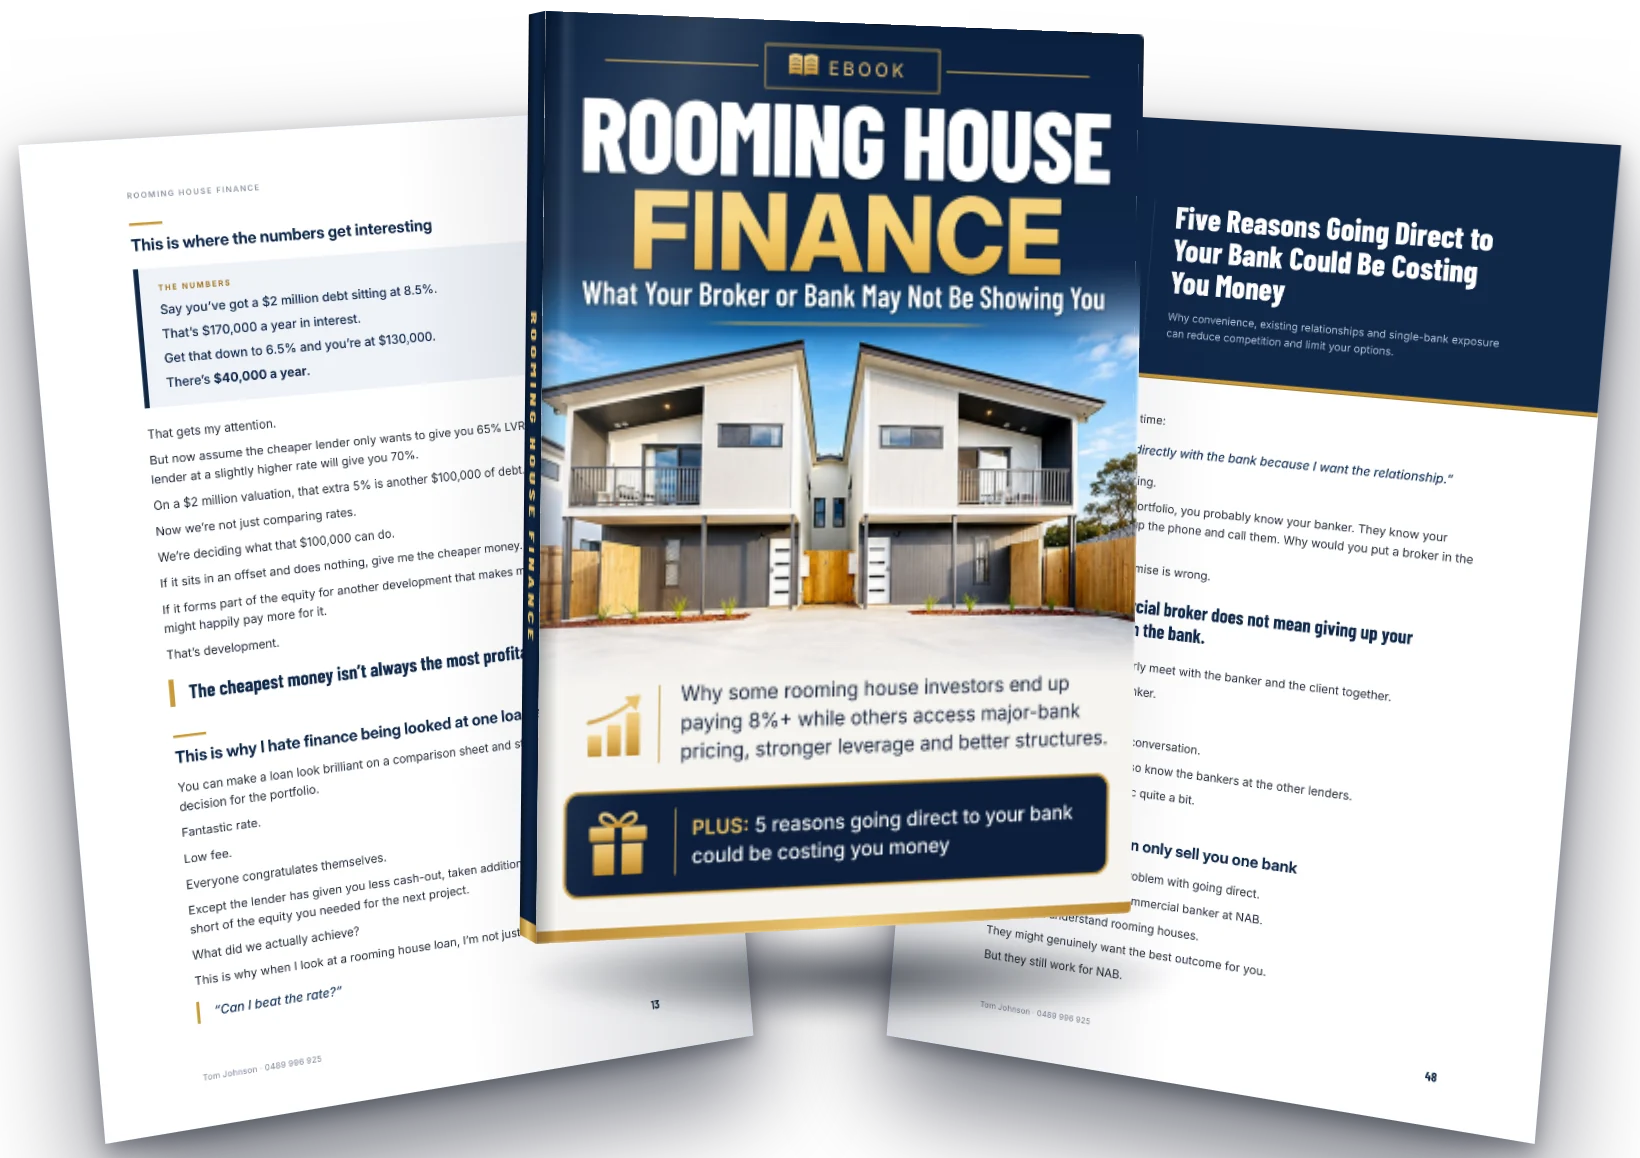
On a $2 million loan, 8.5% versus 6.5% is $40,000 a year. This free 71-page playbook shows you which side of that gap you’re on, and how to fund the next build WITHOUT feeding fresh cash into every project.

The Rooming House Finance playbook, with two inside pages: the $40,000 gap and the bonus chapter
“I’m not looking at your deal like a broker trying to get a loan approved. I’m looking at it like one of my own.”
Tom Johnson, developer and finance specialist

Instant download · 71 pages · For investors who already own or build rooming houses

COMMERCIAL EXCELLENCE
AWARD WINNER
2026
6 rooming houses built, under construction or held for myself
$350M in rooming finance settled
100% five-star reviews

Dear Rooming House Investor,

If you want to keep building rooming houses without your finance slowing you down...

And you want to know you’re not paying more than you need to on the ones you already own...

Then this could be the most useful ten minutes you spend on your portfolio this year.

Some investors keep rolling. They finish a property, lease it up, refinance it and pull their equity back out. Then they do it all again.

But plenty hit a wall at two or three properties and just sit there. Plenty of equity on paper. No cash for the next site.

I know both sides of this because I’m a developer first. I build and hold my own rooming houses, and rooming accommodation finance is all my business does. I own rooming houses in QLD and VIC.
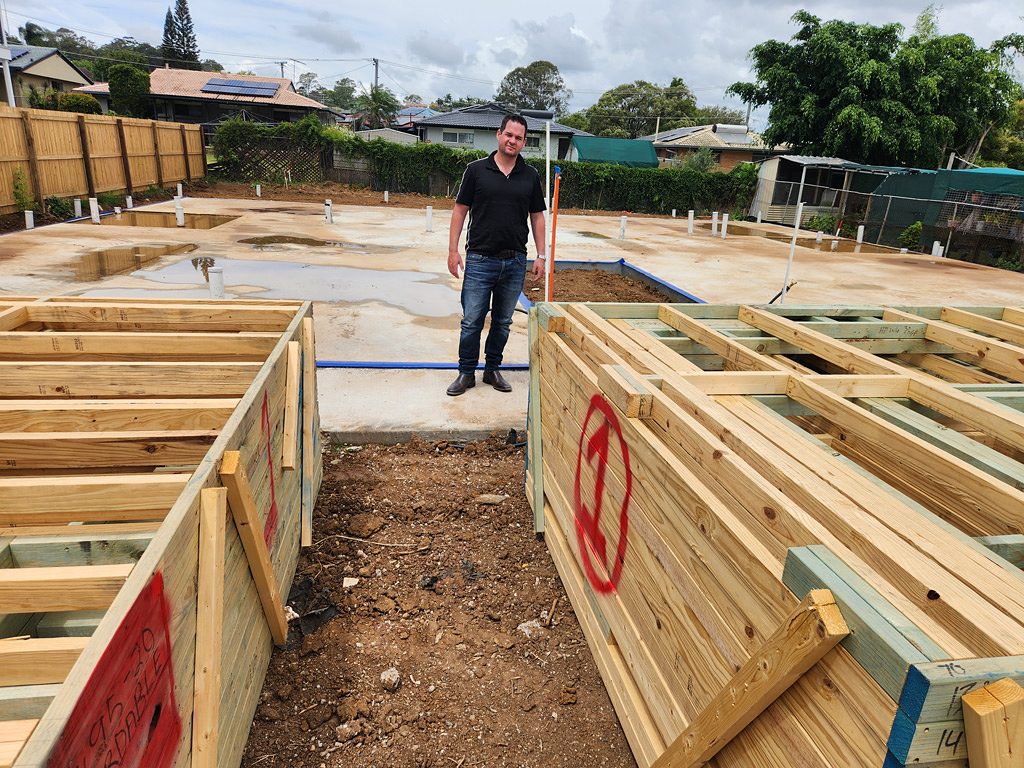
Tom Johnson standing on the slab at one of his rooming house builds, with timber wall frames stacked beside him
On site at one of my own builds.

Here’s what I’ve learned. The investors who keep rolling don’t have better properties. They don’t have nicer bankers. And they’re not just lucky.

They have better structure. Which lender sees the deal. Which valuer looks at it. How the income is presented. And what happens the day the property is finished.

Without that, the same cycle plays out. The build gets funded with expensive money. The property is finished and leased, but nobody goes back and looks at it again. The rate stays at 8%+. The equity stays trapped. So the next deal needs fresh cash, and you wait. Or you take another expensive loan because it’s the only one anyone showed you.

It’s a cycle that turns a growing portfolio into a stalled one.

So I wrote down exactly how I look at finance on my own deals.

It’s called Rooming House Finance: What Your Broker or Bank May Not Be Showing You. 71 pages. 14 chapters, including 5 reasons going direct to your bank could be costing you money. No theory. Just the questions I ask, the numbers I run and the moves I make at each stage.

And right now you can download it free.

Get for free what I learned building and financing my own rooming houses

100% privacy. No spam.
What you’ll discover

Here’s just some of what you’ll discover inside this free playbook...

  • The “same bank, different outcome” problem: why “my broker already has access to that lender” is only half the question, and how one bank can give two brokers completely different answers. Page 26

  • The 1.1x ICR advantage: the assessment I can access with one major lender on suitable deals, and why it changes how much the same income can borrow. Page 34

  • When 8%+ is smart money: and when it just means nobody showed you anything else. Page 10

  • The $40,000 gap: the maths on a $2 million loan at 8.5% versus 6.5%, and why the cheapest money still isn’t always the most profitable money. Page 13

  • The cap rate swing: how the same $100,000 of net income can be valued at $1.67 million or $1.43 million, and what that $168,000 lending gap does to your next deal. Page 29

  • The one question to ask any broker before you hand over a rooming house deal. (Hint: it’s not “are you accredited?”) Page 16

  • The “wrong valuer” trap: how the wrong person on the job can wipe hundreds of thousands off a perfectly good deal. Page 24

  • The equity release refinance: a worked example where one completed property releases $160,000 for the next deal. Page 43

  • The exit-first build: why the refinance gets sorted before construction starts, and how the right lender can sometimes fund a build without a full QS process. Pages 37 and 38

  • The 0.25% portfolio test: what 0.25% is worth on $20 million of debt, and why your bank should be competing for you at that size. Page 55

  • The “do nothing” rule: when the right move is to leave your finance exactly where it is. Page 63

  • BONUS: 5 reasons going direct to your bank could be costing you money, including the one thing your banker simply can’t tell you. Page 48

And much more.

Get for free what I learned building and financing my own rooming houses

100% privacy. No spam.

The 3 shifts

The 3 shifts that separate investors who stall at two or three properties from the ones who keep building

Here’s what a lot of rooming house investors never get told.

  1. 01

    They refinance on completion, every time.

    The construction lender gets the property built, and that’s its job done. The day the property is leased, they test the market again, because a finished, income-producing asset opens up lenders a building site never could.

  2. 02

    They treat the valuation as strategy, not admin.

    They know which valuers understand the asset, and they have the rent roll, expenses and comparable sales ready before the lender is even chosen. At 70% LVR, a $300,000 better valuation is $210,000 more to work with.

  3. 03

    They keep every property standing on its own.

    One property, one entity, one loan. So they can refinance one, sell one or pull equity from one without untangling the rest, and no single bank gets its hands on the whole portfolio.

You don’t need a bigger portfolio or a better banker to do any of this. You need the system. And the system is what’s inside the playbook.

Get for free what I learned building and financing my own rooming houses

100% privacy. No spam.

Who is Tom Johnson?

Who is Tom Johnson to make these claims?

Fair question.

I got into rooming accommodation as a developer first. I was building and holding these properties before I ever started financing them for other people.

Today, rooming accommodation is all my finance business does. I’m talking to banks, commercial lenders and valuers in this space every week. I know which bankers understand the asset class, which valuers I want looking at these properties, and which lenders are sharp on ICR.

And I still develop. So when I look at your deal, I look at it like one of my own: how much cash goes in, how much can come back out, and what it lets you do next.

I don’t care which lender wins. I care whether the finance makes sense. That’s why I’m giving away the playbook I use on my own deals.

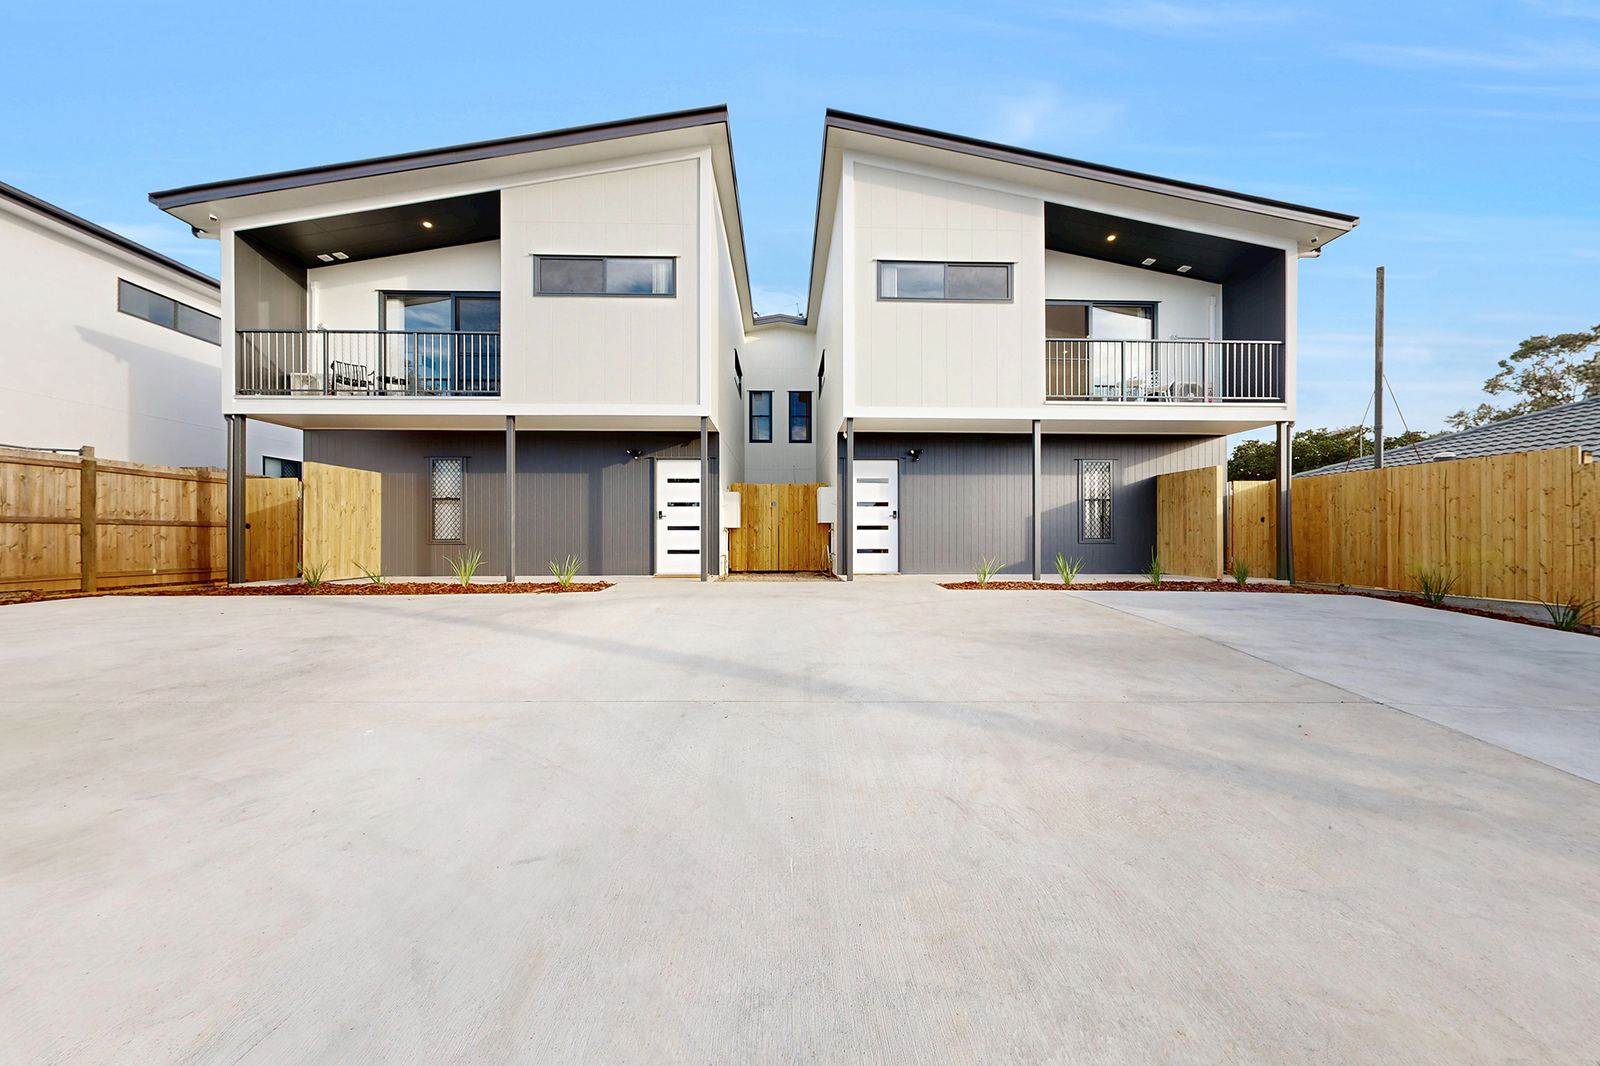
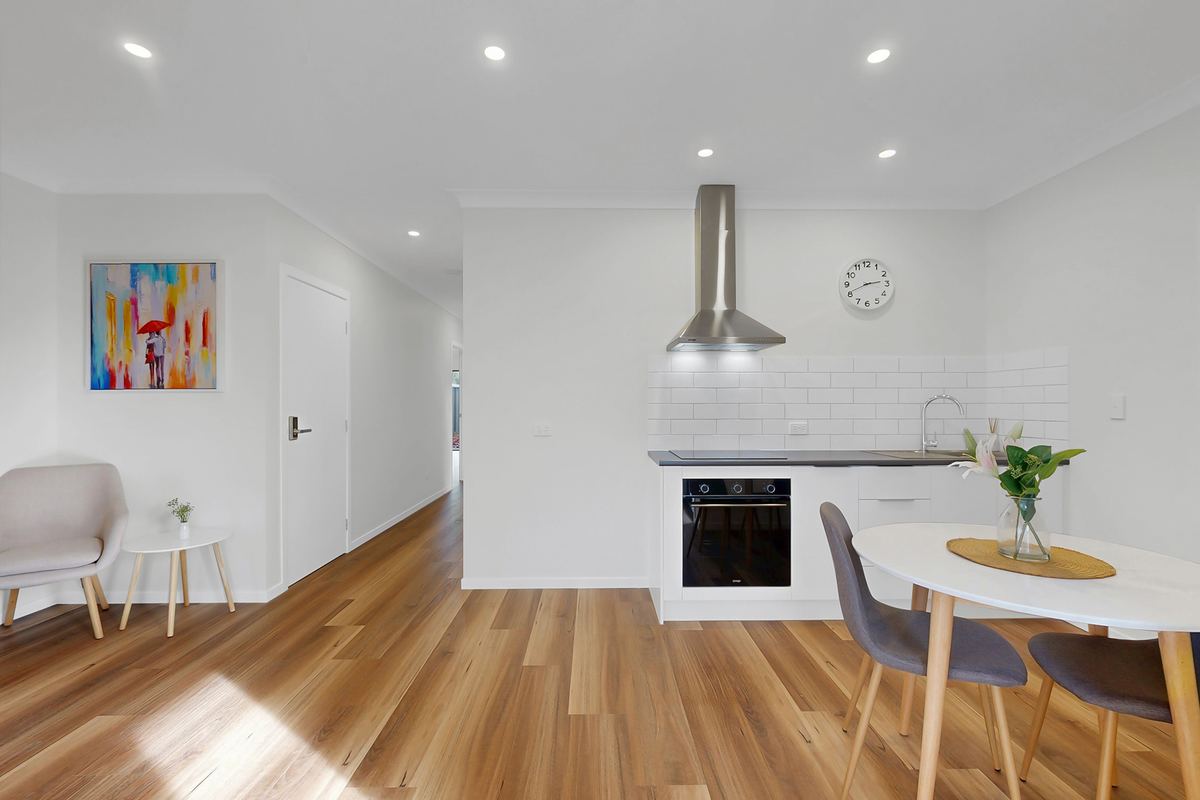
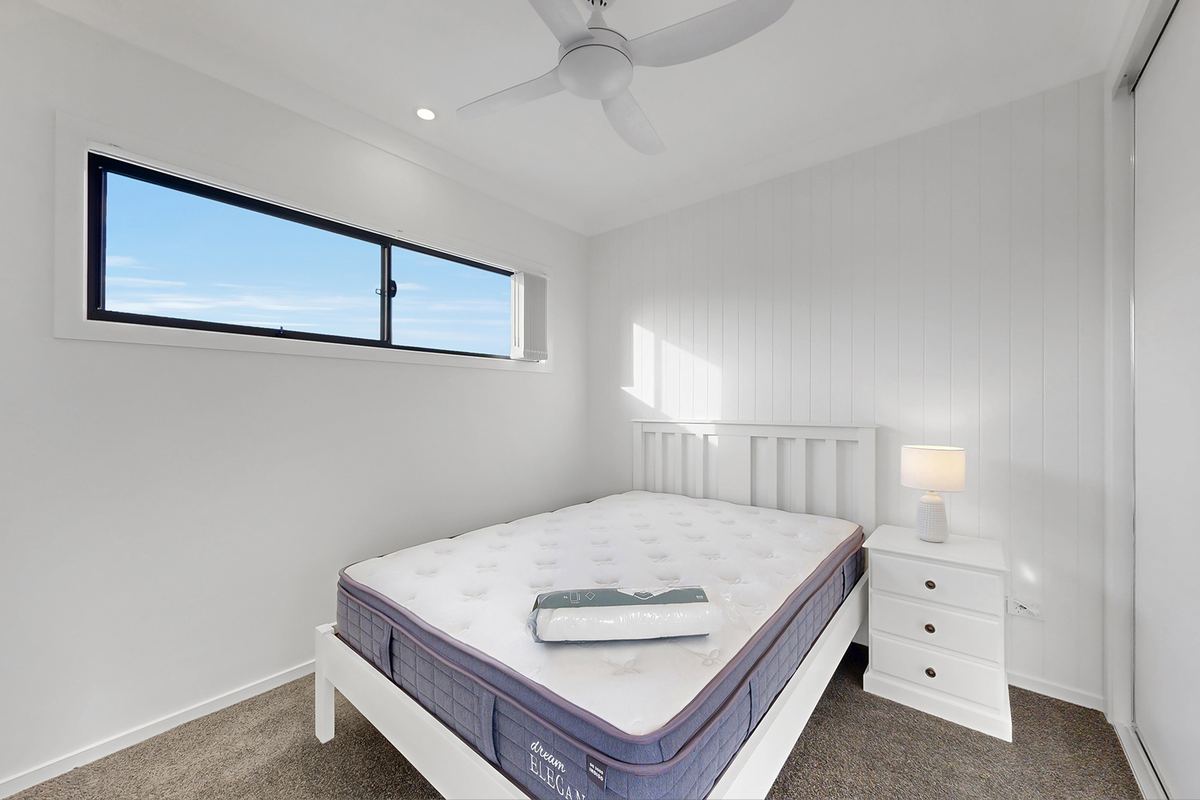
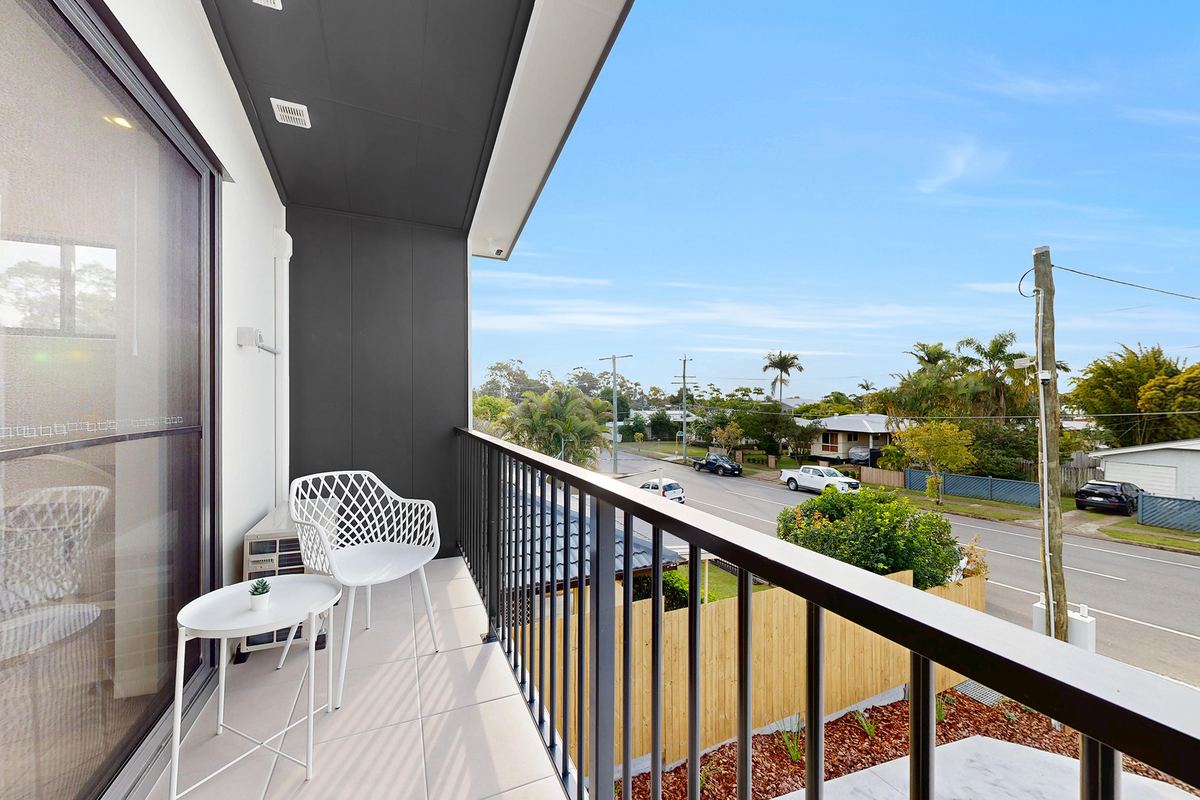
Front of one of Tom’s completed rooming houses: two townhouse-style buildings with a shared driveway Shared kitchen and dining area Upstairs balcony looking over the street Furnished bedroom with ceiling fan and built-in wardrobe

One of my completed rooming houses, inside and out.

Get for free what I learned building and financing my own rooming houses

100% privacy. No spam.

Download your free playbook now, before your next refinance or build

This free playbook is everything I look at when I finance my own rooming houses. It’s 71 pages. It’s plain English. And you can use it on your own loans tonight.

Don’t wait until settlement is four weeks away to find out your lender won’t fund the next deal. The best time to look at your structure is when you’re not under pressure.

So go ahead. Get for free what I learned building and financing these properties myself.

Rooming House Finance: What Your Broker or Bank May Not Be Showing You, the free playbook

Send me my free playbook now

GET MY FREE PLAYBOOK

100% privacy. No spam. Your playbook arrives by email straight away, and my team or I may give you a quick call to see if a second opinion would help.

TOM JOHNSON Rooming Accommodation Finance

General information only. Not credit, financial, tax or legal advice. Rates and scenarios are illustrative, and lender criteria and approval apply.

© 2026 Tom Johnson · Privacy policy · Terms

Free instant download

Send me my free playbook now

GET MY FREE PLAYBOOK

100% privacy. No spam. Your playbook arrives by email straight away, and my team or I may give you a quick call to see if a second opinion would help.